Chart Kid Matt had an excellent post this past week that listed 10 reasons to be bullish.
Each reason is attached to a chart. I won’t spoil the entire post (you should read it) but this one tells the biggest story as far as I’m concerned:
Earnings growth is accelerating. Margins are still high. The bull market is broadening out in terms of leadership. The fundamentals of the stock market are screaming bullish right now which is why stocks have been moving higher.
But I am also a fan of looking at both sides of the market because it’s important to understand where any market narrative could be wrong.
Markets are nothing if not cyclical.
There is no certainty when it comes to thinking through future market outcomes, only a range of possibilities.
So let’s play devil’s advocate and also look at 10 reasons to be bearish:
1. Most of the hyperscaler capex is circular. This might be the chart of the year:
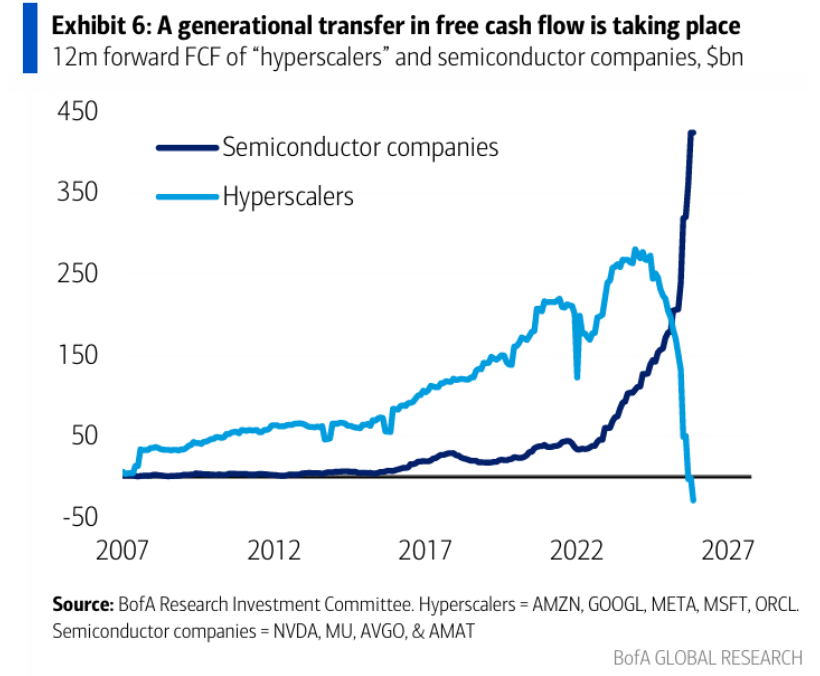
Free cash flow from the hyperscaler stocks is crashing. Those cash flows are being transferred to the semiconductor companies for the AI buildout.
This can’t possibly last…right?
What happens if that’s all there is?
What if the capex slows?
What if the investment from outside the tech companies doesn’t transpire soon enough?
2. The Mag 7 are underperforming. The good news is the market leadership is broadening to different segments of stocks.
The bad news is the Mag 7 stocks are struggling and still makes up roughly one-third of the S&P 500.
Every single Mag 7 stock outside of Apple is in the midst of a double-digit drawdown from the highs:
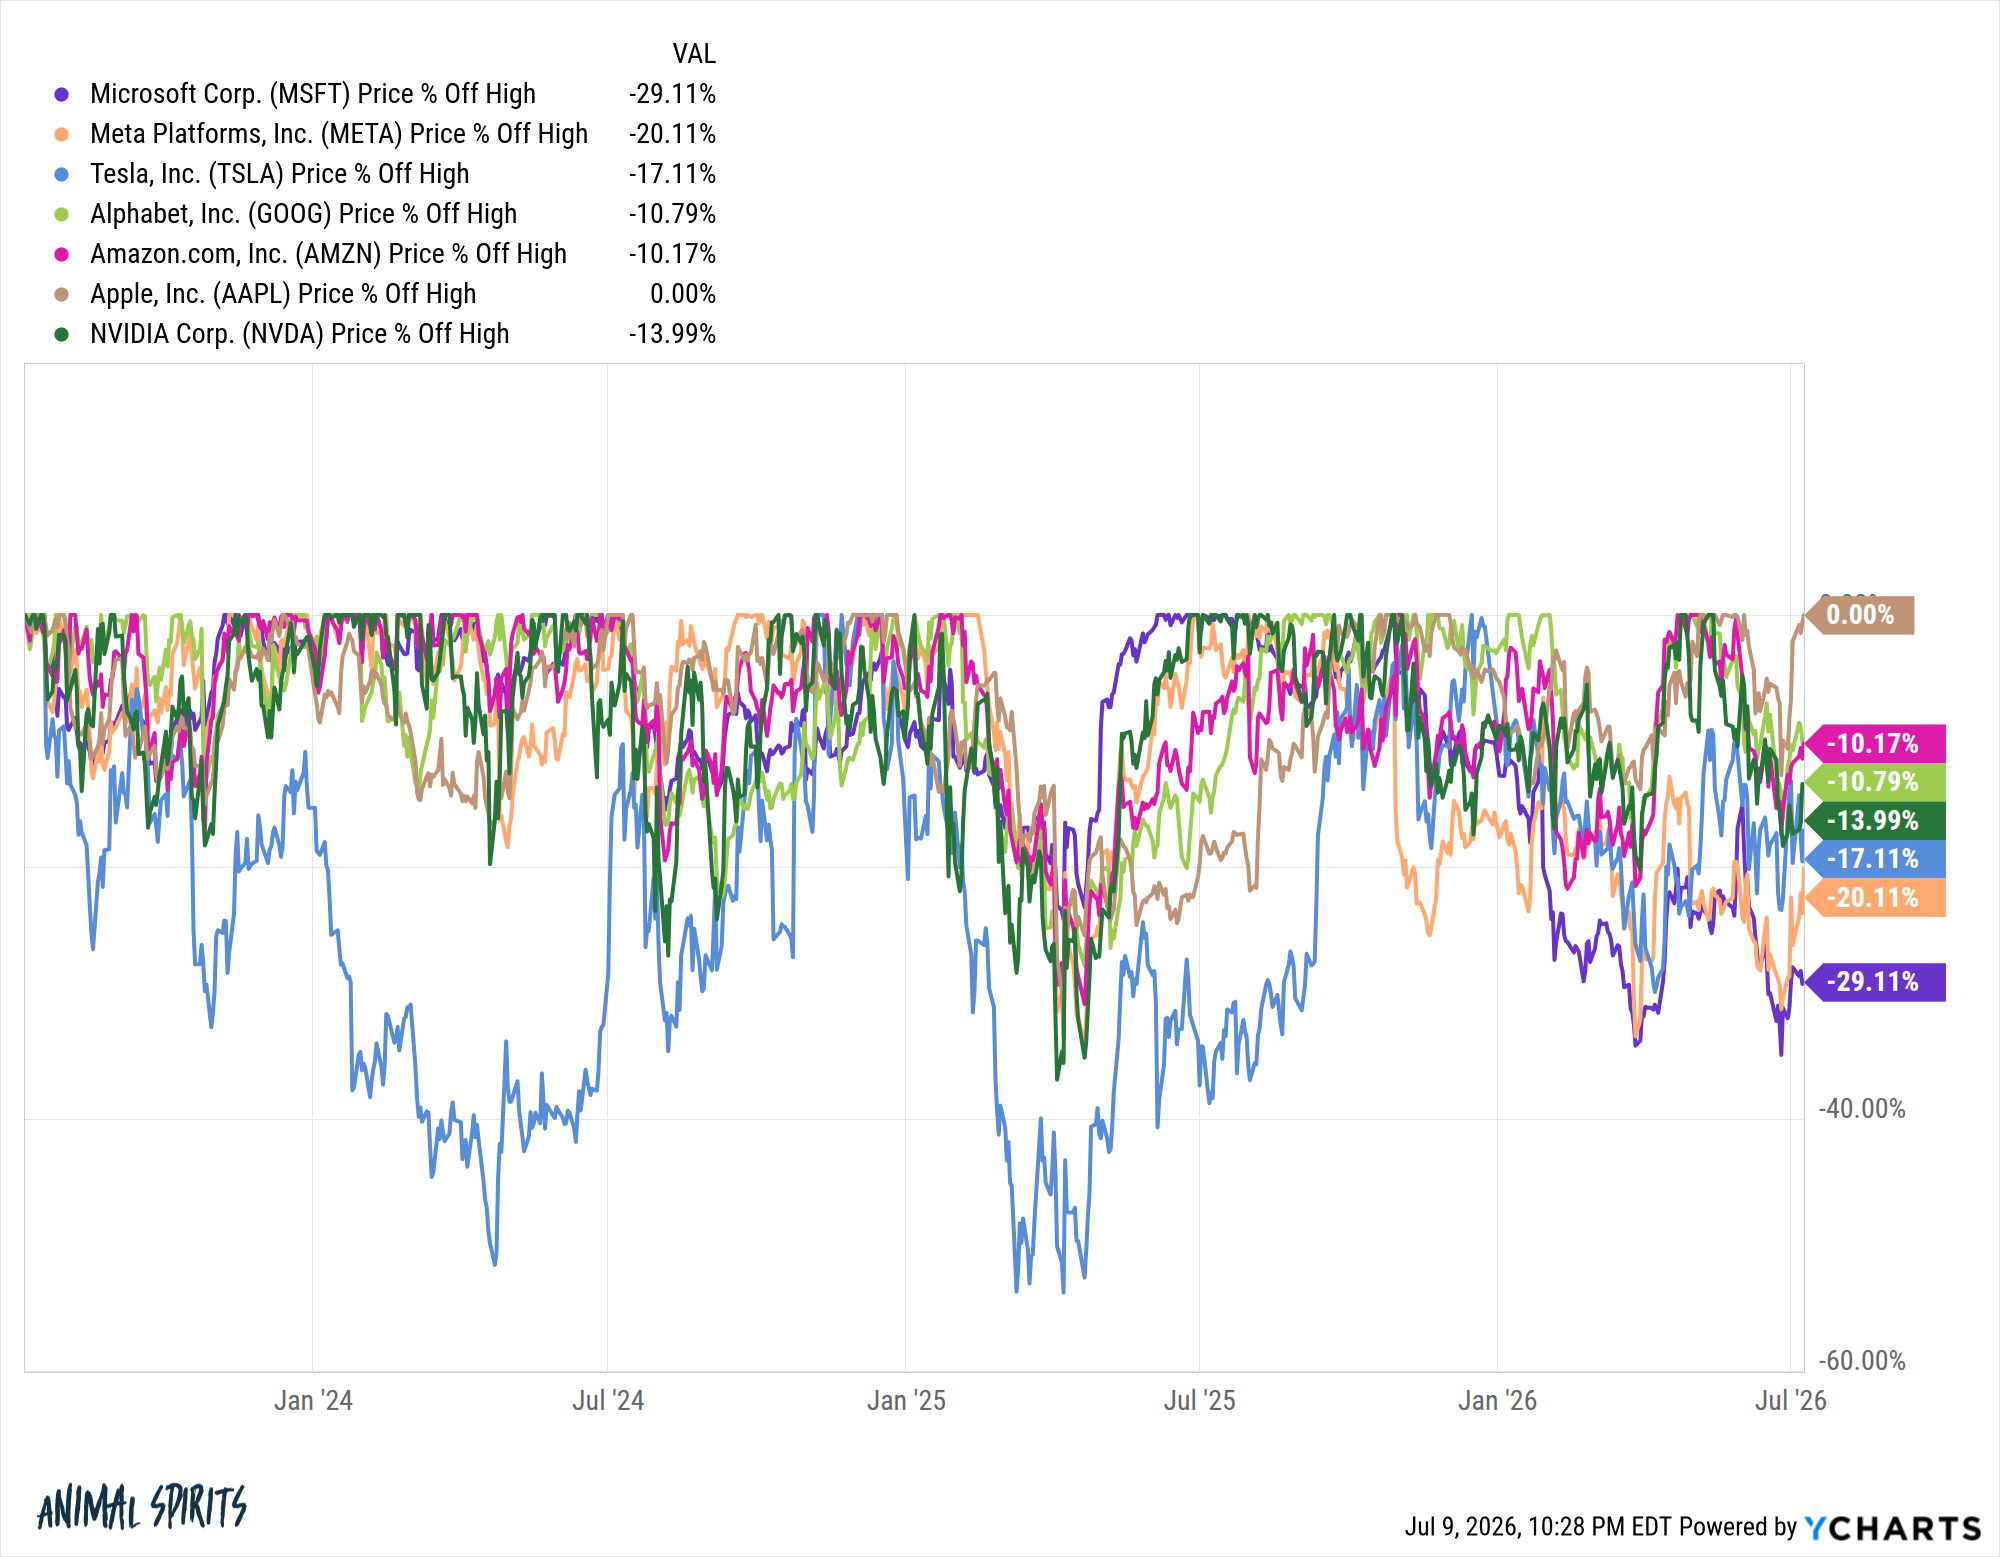
If these stocks completely fall out of bed eventually it’s going to impact the overall market.
3. AI is bleeding into the economy. Michael Cembalest has some charts that show AI’s impact on the economy:
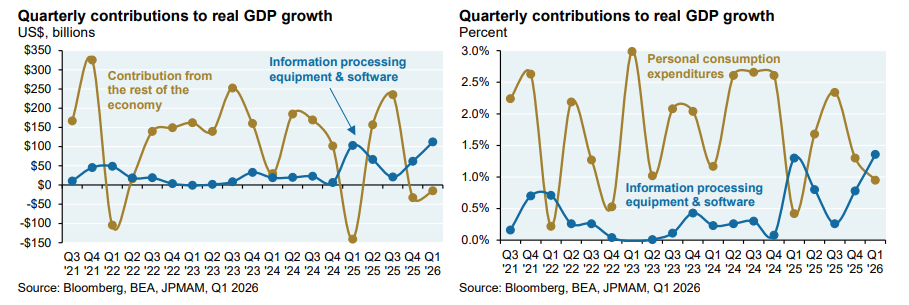
An AI slowdown could actually lead to an economic slowdown. This is not just the stock market story.
4. Retail is all in. According to Citadel Securities retail investors are deploying capital at a record pace:
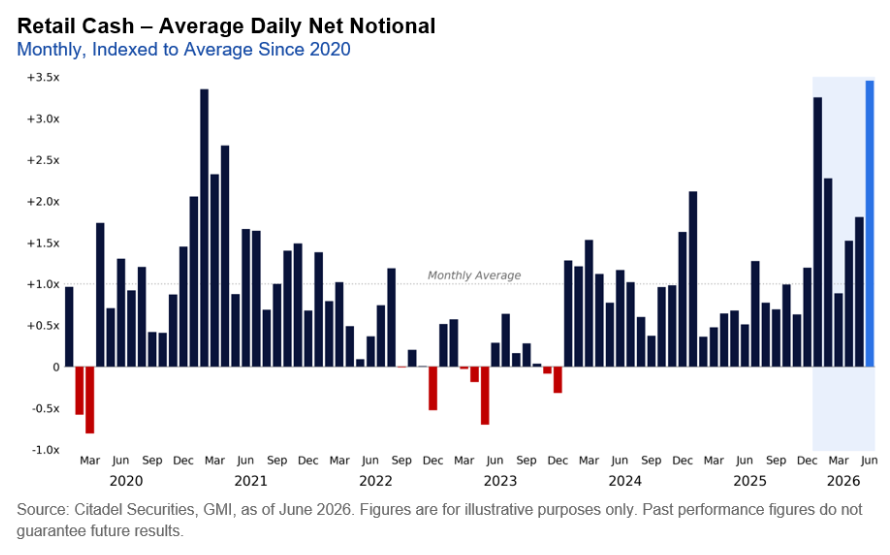
Retail investors are all-in on IPOs, options, futures, leveraged ETFs and stocks.
5. Inflation remains high. The Iran war has sent inflation back above 4%:
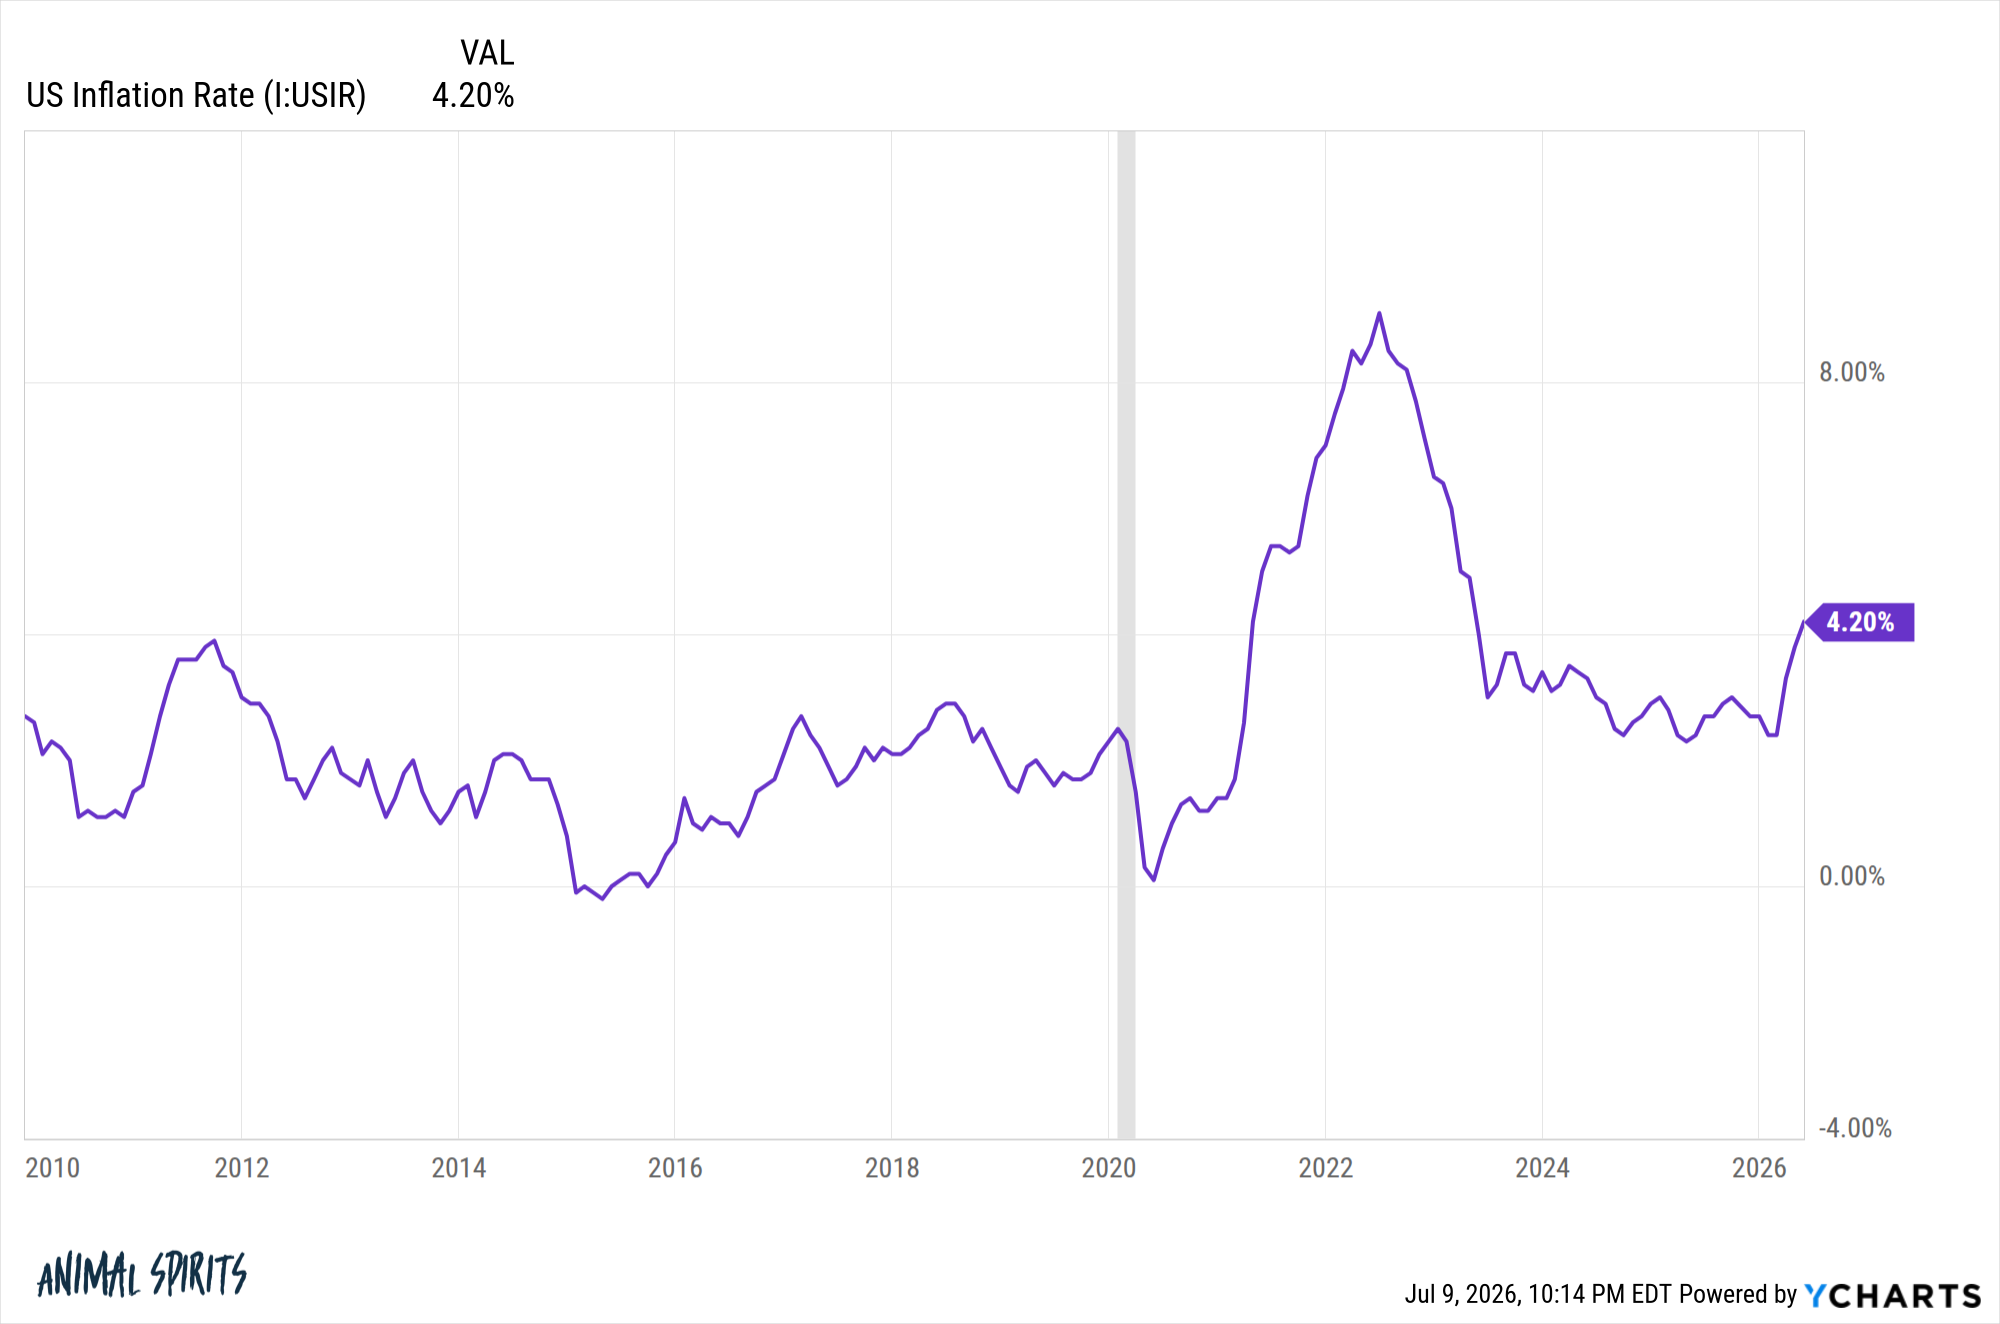
The hope is this is a temporary spike but if inflation is sticky, that’s a headwind to the economy.
6. Mortgage rates are still high. Higher inflation means higher interest rates. The 30 year fixed rate mortgage is close to 7% yet again:
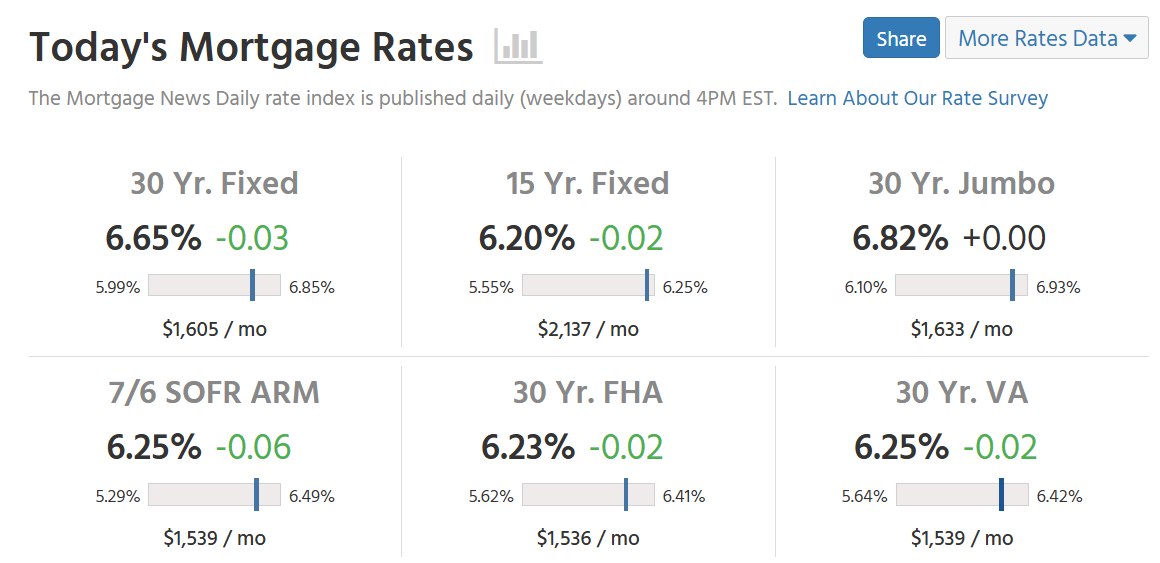
Housing is a big part of the economy. Some have said housing is the economy.
The housing recession hasn’t mattered yet. How long can this last without some real damage?
7. Complacency. The S&P 500 was up 10% in the first six months of this year.
That’s following gains of 18%, 25% and 26% in 2025, 2024 and 2023, respectively.
It’s quite possible stability will breed instability and we’re setting ourselves up for a Minsky moment.
8. AI checks all the bubble boxes. Artificial intelligence checks all of the bubble boxes.
Technological revolution? Check.
Capex binge? Check.
Bull market in stocks? Check.
Leverage in the system? Check.
FOMO kicking in? Check.
Retail speculation? Check.
It sure feels like this could be a bubble or turn into one.
9. We’re due for a recession. There was a two month recession in the spring of 2020 because of Covid. It doesn’t count as a real recession because the government threw so much money at the problem.
It wasn’t a true economic cycle. It was man made and shored up immediately.
That makes it’s been 17 years since the last true recession in America:
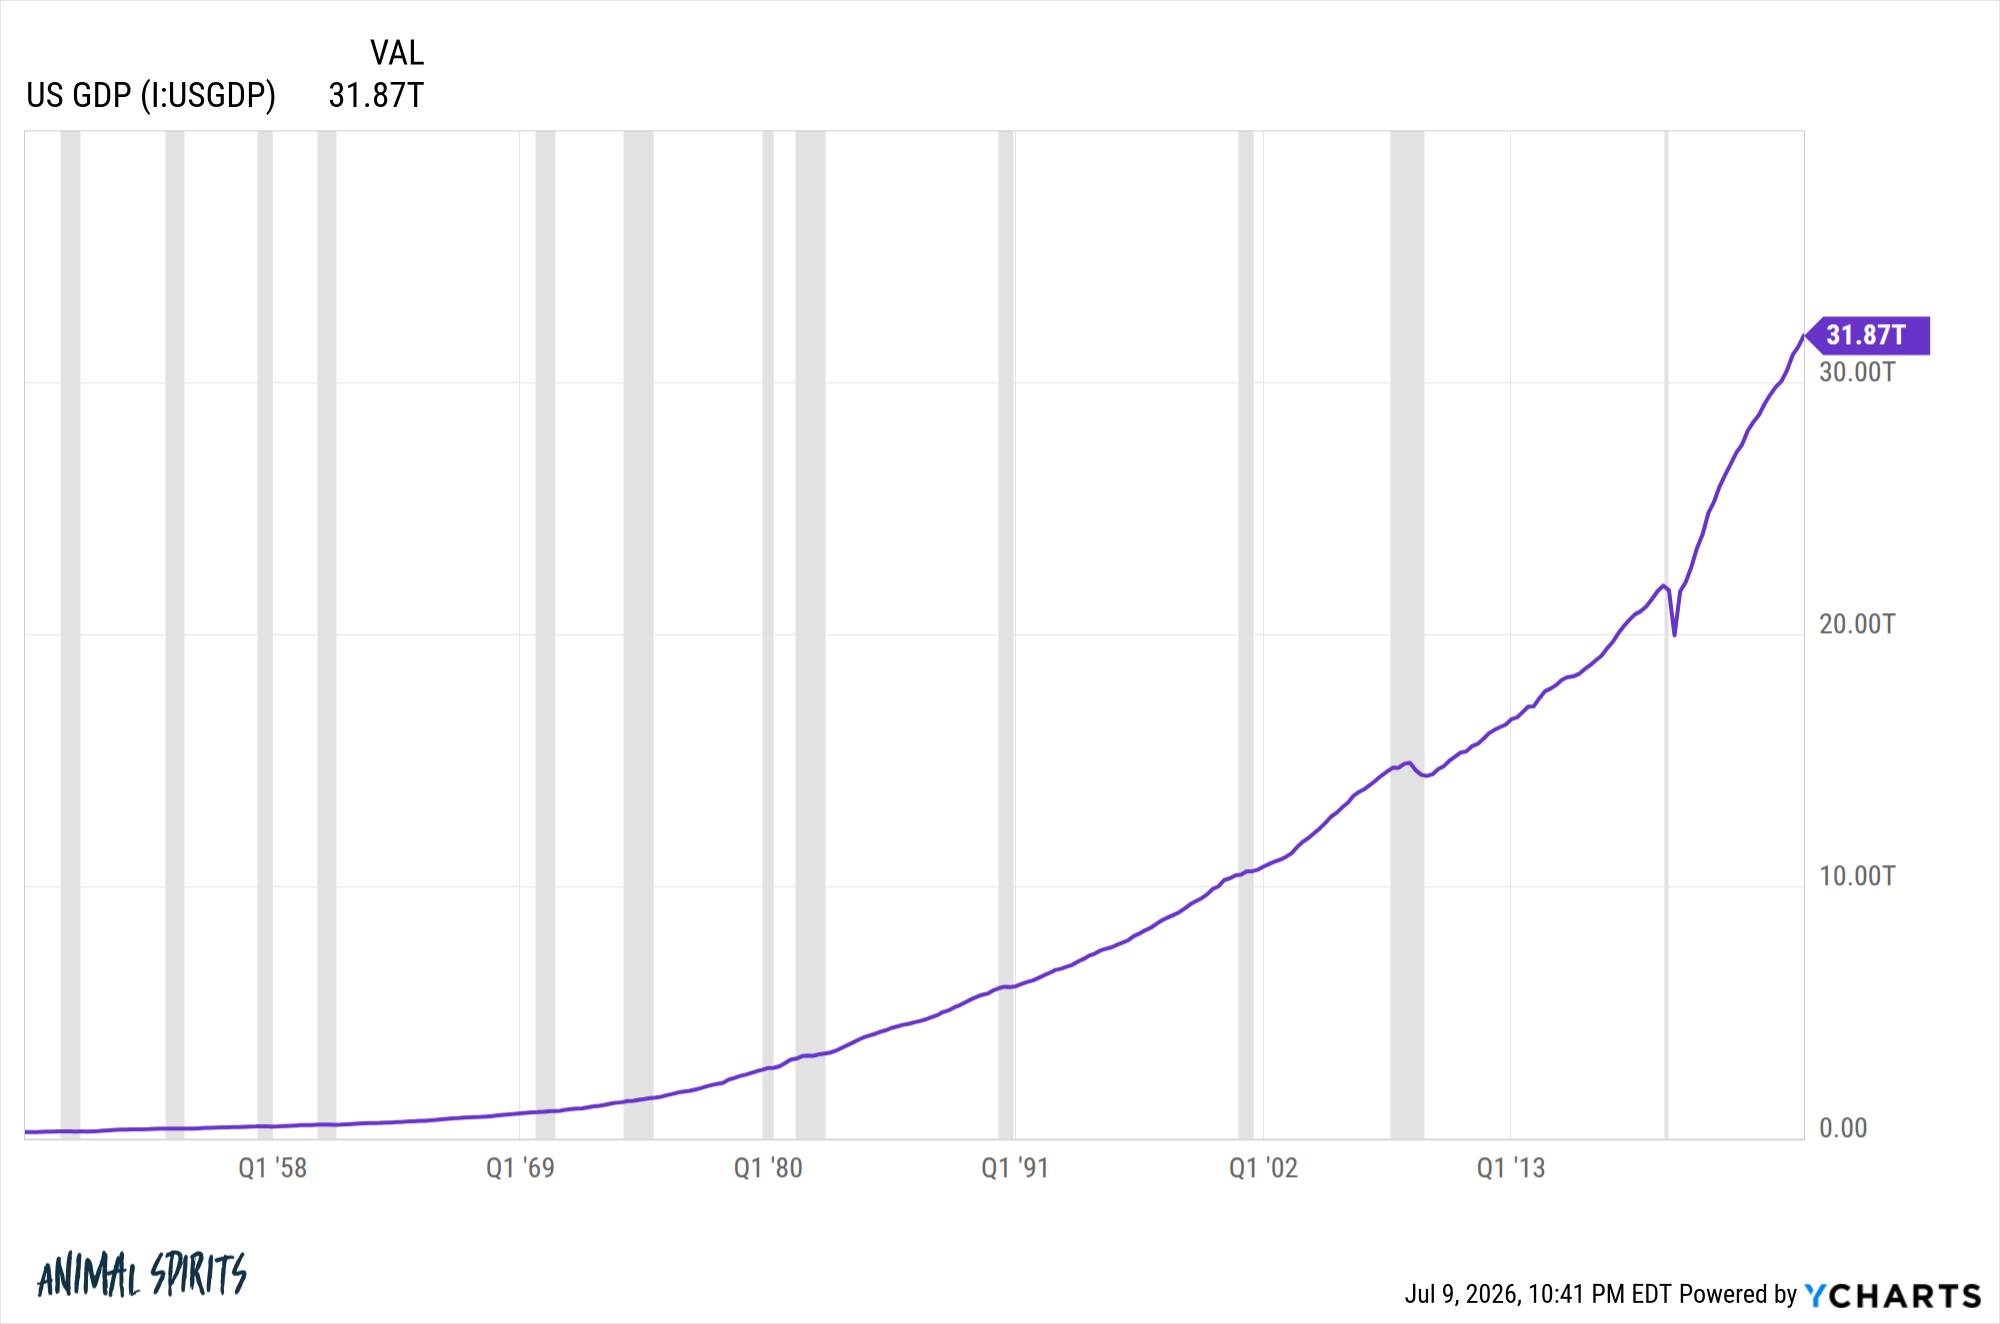
Have we outlawed recessions?
It’s possible we’re due for a slowdown.
10. Returns have been too good. From the bottom of the 2022 bear market, the S&P 500 is up nearly 24% annualized:
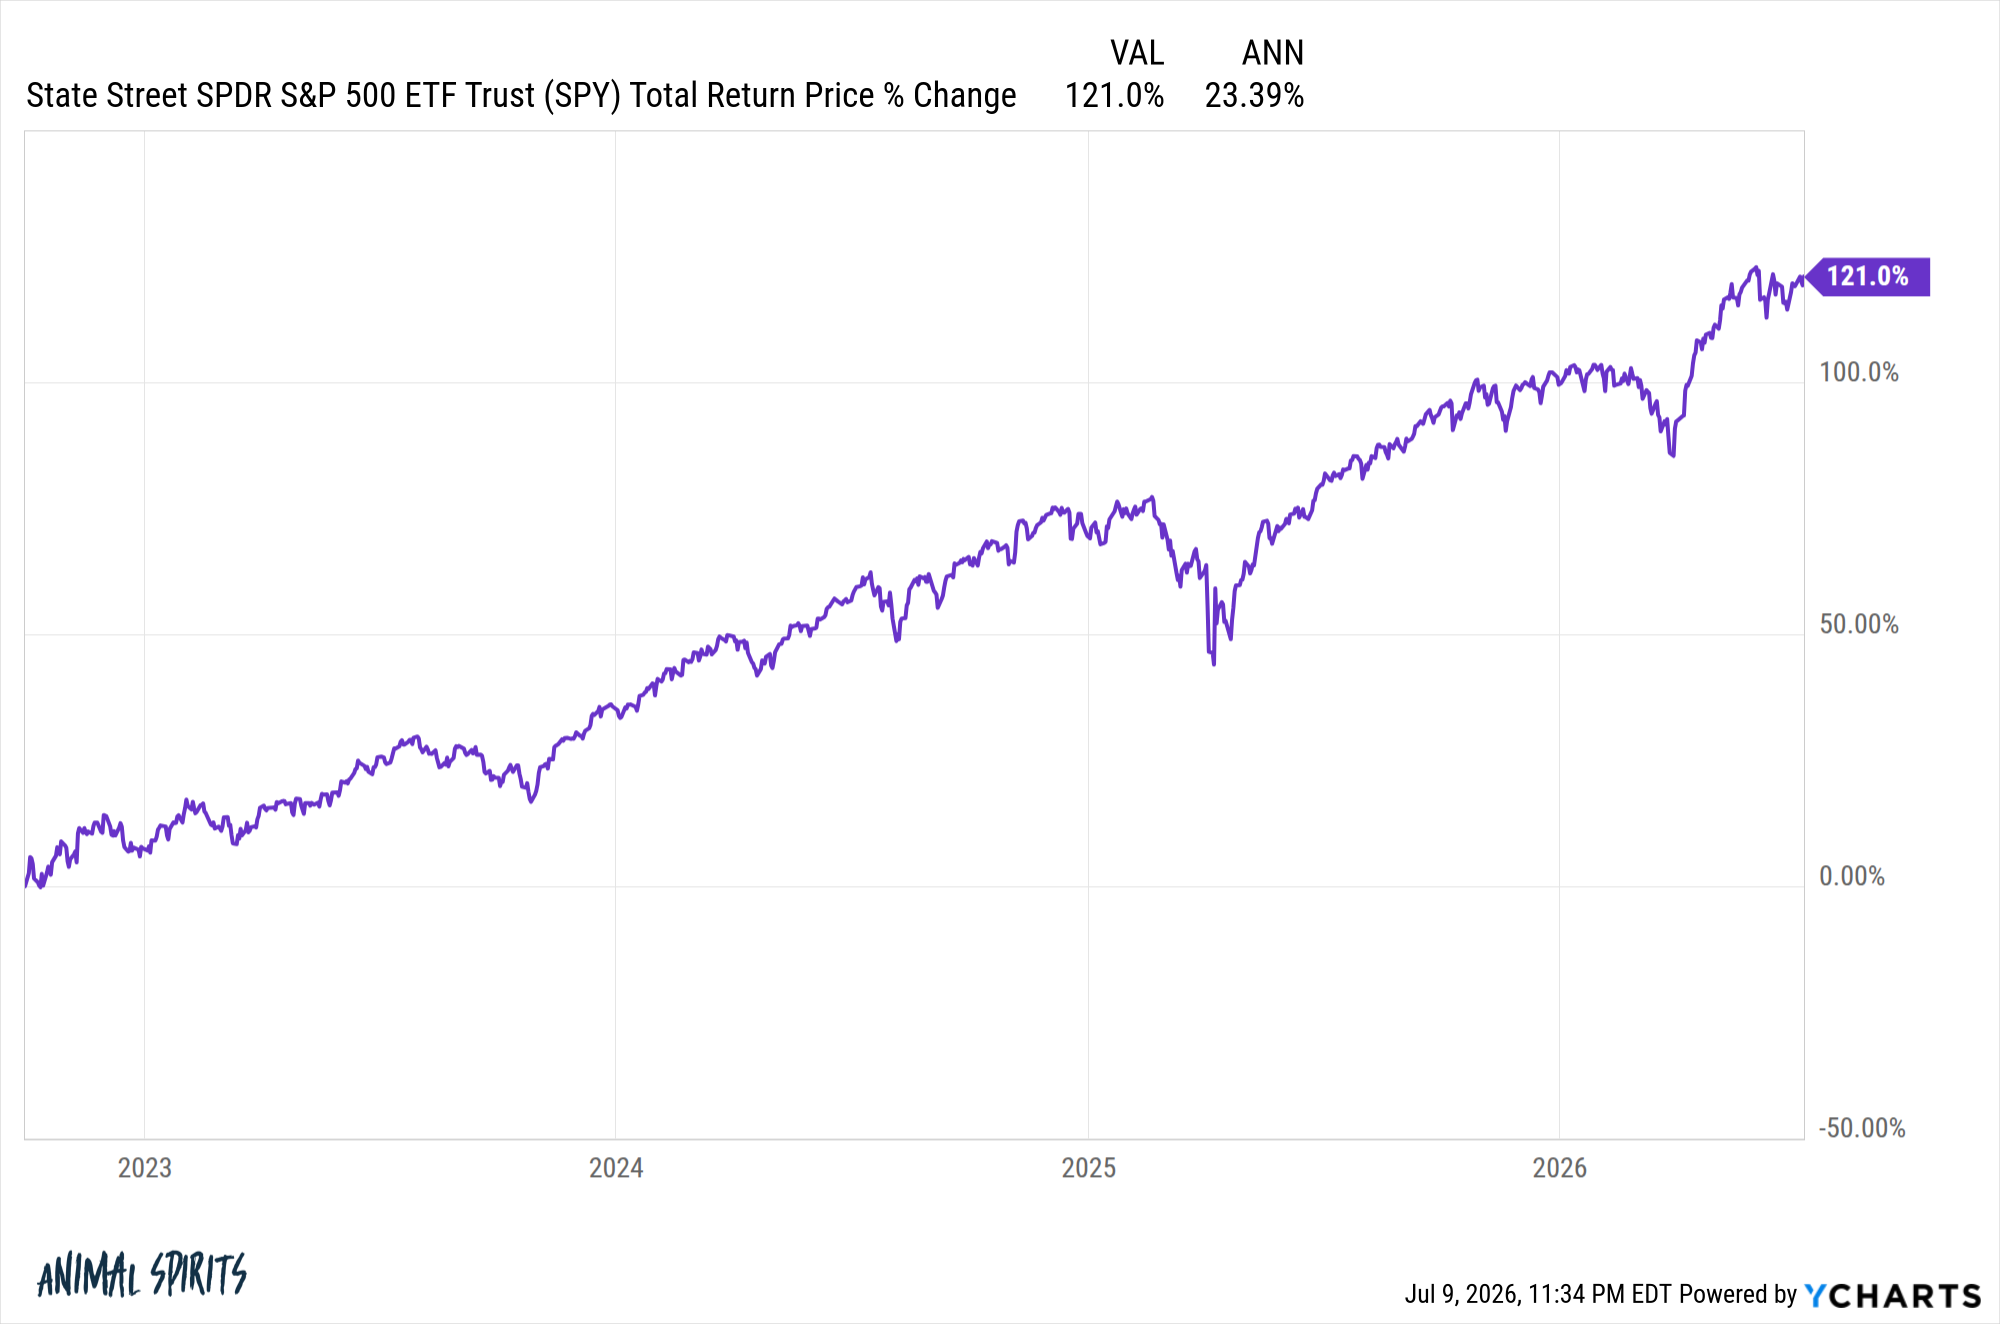
From the Covid lows in late-March 2020, the S&P is up 23% per year.
Are these returns cherry-picked from the lows? Of course! But the bull market this decade has been spectacular.
Sometimes the biggest reasons stocks go down is because they went up too much in the first place.
Do you believe the bullish indicators?
Or the bearish indicators?
That’s the trillion dollar question.
Michael and I talked about reasons to be bullish, bearish and much more on this week’s Animal Spirits video:
Subscribe to The Compound so you never miss an episode.
Further Reading:
Tops and Bottoms
Now here’s what I’ve been reading lately:
Books: